
Nearshoring and Just-in-Case Reshape EU Warehousing Demand

 Author: Pickup2 Team
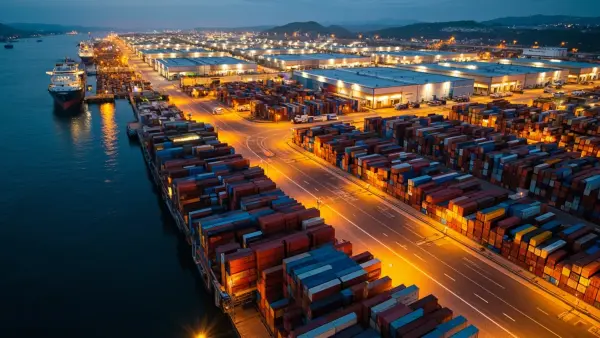
European warehousing is entering a new era as supply chain resilience overtakes pure cost optimisation.
Europe's logistics real estate market is undergoing a structural transformation. Manufacturers, retailers, and industrial producers are no longer chasing the cheapest warehouse footprint — they are prioritising proximity, redundancy, and operational flexibility. The result is a sustained appetite for new and modern logistics space, even as broader economic signals remain mixed across the continent and consumer demand fluctuates.
Nearshoring Reshapes the Map
Production is moving closer to European end markets at scale. According to Savills' European Logistics Spotlight for Q2 2026, nearshoring has become a defining force behind occupier demand, with companies relocating or duplicating capacity in regions closer to consumers to reduce exposure to long-haul disruption. Turkey, North Africa, and parts of Eastern Europe are emerging as preferred production bases, while Iberian and Italian corridors are seeing renewed occupier interest as reshoring accelerates.
The effect on warehousing demand is direct and measurable. Shorter, more predictable supply chains require fewer but better-located facilities, and occupiers are increasingly willing to commit to long leases in proven micro-markets. Demand is concentrating in mid-box and large-box warehouses between 10,000 and 50,000 square metres, particularly where road, rail, and sea connectivity intersect. Vacancy rates in prime European logistics hubs remain near historic lows, even as speculative development continues at pace across the continent.
Just-in-Case Replaces Just-in-Time
Inventory strategy is shifting fundamentally across European supply chains. The lean, just-in-time model that defined the 2010s has given way to a just-in-case approach, with companies willingly absorbing higher carrying costs in exchange for buffer capacity and supply security. This translates directly into more pallet positions, more cubic metres, and longer lease commitments than the pre-pandemic norm.
Key signals from the market include:
- Occupiers signing pre-leases 12 to 18 months before operations begin
- Average lease terms extending beyond the historical five-year benchmark
- Growing demand for temperature-controlled and high-specification space
- Increased willingness to pay premium rents for strategically located facilities
The Europe Logistics Market outlook points to sustained mid-single-digit annual growth in modern warehouse stock requirements through 2034, driven by these structural inventory shifts alone.
Port-Centric Hubs Capture the Premium
Coastal and port-adjacent logistics real estate is emerging as the most contested segment of the European market. Savills reports that port-hinterland warehouse stock continues to outperform the wider market, supported by containerised trade growth, Red Sea rerouting effects, and the need for rapid cross-border distribution. Antwerp, Rotterdam, Hamburg, Valencia, and Piraeus are all seeing record or near-record occupancy, with several markets now effectively supply-constrained.
These hubs benefit from a powerful combination of deep-water access, mature road and rail connections, and growing nearshoring flows from North Africa and the Levant. For occupiers, the calculus is straightforward: proximity to throughput and modal choice outweighs the marginal cost savings available in lower-tier inland locations. Developers are responding, but new speculative supply will take time to deliver, keeping upward pressure on rents through 2026 and beyond.
Conclusion
The European warehousing market is being redrawn by resilience-led decision making. Nearshoring and just-in-case inventory are not temporary reactions to recent disruptions — they are structural shifts that will continue to drive demand for well-located, high-quality logistics space. Platforms like Pickup2 help shippers, forwarders, and carriers navigate this evolving landscape by matching available capacity to shifting demand in real time.